
Category Archives: For Buyers

Auto Added by WPeMatico

Don’t Let Fear Stop You from Applying for a Mortgage

Don't Let Fear Stop You from Applying for a Mortgage | Simplifying The Market

A considerable number of potential buyers shy away from jumping into the real estate market due to their uncertainty about the buying process. A specific cause for concern tends to be mortgage qualification.

For many, the mortgage process can be scary, but it doesn’t have to be!

In order to qualify in today’s market, you’ll need to have saved for a down payment (73% of all buyers made a down payment of less than 20%, with many buyers putting down 3% or less), a stable income and good credit history.

Throughout the entire home buying process, you will interact with many different professionals, all of whom perform necessary roles. These professionals are also valuable resources for you.

Once you’re ready to apply, here are 5 easy steps that Freddie Mac suggests you follow:

  1. Find out your current credit history & score – even if you don’t have perfect credit, you may already qualify for a loan. The average FICO® Score of all closed loans in September was 724, according to Ellie Mae.
  2. Start gathering all your documentation – income verification (such as W-2 forms or tax returns), credit history, and assets (such as bank statements to verify your savings).
  3. Contact a professional – your real estate agent will be able to recommend a loan officer that can help you develop a spending plan, as well as determine how much home you can afford.
  4. Consult with your lender – he or she will review your income, expenses, and financial goals to determine the type and amount of mortgage you qualify for.
  5. Talk to your lender about pre-approval – a pre-approval letter provides an estimate of what you might be able to borrow (provided your financial status doesn’t change), and demonstrates to home sellers that you are serious about buying!

Bottom Line

Do your research, reach out to professionals, stick to your budget, and be sure that you are ready to take on the financial responsibilities of becoming a homeowner.
Renting or Buying…Either Way, You’re Paying Someone’s Mortgage

Renting or Buying…Either Way, You're Paying Someone's Mortgage | Simplifying The Market

There are some people who have not purchased homes yet because they are uncomfortable taking on the obligation of a mortgage. Everyone should realize that, unless you are living with your parents rent-free, you are paying a mortgage – either yours or your landlord’s.

As Entrepreneur Magazine, a premier source for small business, explained in their article, “12 Practical Steps to Getting Rich,”

“While renting on a temporary basis isn’t terrible, you should most certainly own the roof over your head if you’re serious about your finances. It won’t make you rich overnight, but by renting, you’re paying someone else’s mortgage. In effect, you’re making someone else rich.”

Christina Boyle, Senior Vice President and head of the Single-Family Sales & Relationship Management organization at Freddie Mac, explains another benefit of securing a mortgage vs. paying rent:

“With a 30-year fixed rate mortgage, you’ll have the certainty & stability of knowing what your mortgage payment will be for the next 30 years – unlike rents which will continue to rise over the next three decades.”

As an owner, your mortgage payment is a form of ‘forced savings’ which allows you to build equity in your home that you can tap into later in life. As a renter, you guarantee the landlord is the person with that equity.

Interest rates are still at historic lows, making it one of the best times to secure a mortgage and make a move into your dream home. Freddie Mac’s latest report shows that rates across the country were at 3.94% last week.

Bottom Line

Whether you are looking for a primary residence for the first time or are considering a vacation home on the shore, now may be the time to buy.

Buying a Home Can Be Scary… Unless You Know the Facts [INFOGRAPHIC]

Buying a Home Can Be Scary... Unless You Know the Facts [INFOGRAPHIC] | Simplifying The Market

Some Highlights:

Many potential homebuyers believe that they need a 20% down payment and a 780 FICO® score to qualify to buy a home, which stops many of them from even trying! Here are some facts:

  • 40% of millennials who purchased homes this year have put down less than 10%.
  • 76.4% of loan applications were approved last month.
  • The average credit score of approved loans was 724 in September.

How to Save on a Mortgage Payment Whether Buying or Selling

How to Save on a Mortgage Payment Whether Buying or Selling | Simplifying The Market

In Trulia’s recent report, Rent vs. Buy: Roommate Edition, they examined the impact that renting with a roommate has in determining whether it is more expensive to rent or buy. The study explains:

“Since we started keeping track in 2012, it’s been a better deal to buy than rent in America’s largest housing markets – and for much of that time it hasn’t been close.”

It then goes on to ask the question:

“But does the equation change for renters who share their rent with a roommate?”

The report reveals:

“While the standard rent vs. buy analysis reveals buying is cheaper than renting in all of the nation’s 100 largest metros, this doesn’t hold true for those choosing between renting with a roommate and buying a starter home.”

It seems obvious that sharing the cost of renting your living space by taking in a roommate dramatically decreases your housing expense (which is exactly what the report concluded), but it got us thinking.

What if you purchased a home and took in that same roommate?

The savings you would gain by adding a roommate would also occur if you purchased a home. This presents an opportunity for a list of possible purchasers. Here are two examples:

  1. The first-time buyer: As the report explains, many young adults already live with a roommate. If they purchased a new home, perhaps that roommate (or someone else) would be willing to rent a room in their new house. The rent could help offset the mortgage payment.
  2. The empty-nester seller looking to move: Their home may no longer fit their current lifestyle. They may now be looking for something a little smaller with all the bedrooms on the ground level. These families may be able to open a bedroom to an older family member (parents, aunts & uncles, etc.). This would kill two birds with one stone.

A smaller, move-down home is almost impossible to find in the current housing market. If the seller-turned-buyer takes on a tenant, they could buy a more expensive home knowing that the additional monies needed to pay the mortgage would be offset with the additional monies they receive in rent. Secondly, the older couple (ex. parents) could get a housing option that probably far surpasses anything else available to them in the current market.

Bottom Line

Considering the concept of renting a portion of your house to be able to purchase the perfect home may make sense to many families. You will need to decide if it is right for you.

The #1 Reason to List Your House, NOW!

The #1 Reason to List Your House, NOW! | Simplifying The Market

The National Association of Realtors (NAR) released the results of their latest Existing Home Sales Report which revealed that sales rose 0.7% month-over-month, but remain 1.5% lower than they were a year ago. Some may look at these numbers and think that now is not a good time to sell their house, but in fact, the opposite is true.

The national slowdown in sales is directly tied to a lack of inventory available for the buyers who are out in the market looking for their dream homes! The inventory of homes for sale has fallen year-over-year for the last 28 months and has had an upward impact on home prices.

NAR’s Chief Economist Lawrence Yun had this to say,

“Home sales in recent months remain at their lowest level of the year and are unable to break through, despite considerable buyer interest in most parts of the country.

Realtors® this fall continue to say the primary impediments stifling sales growth are the same as they have been all year: not enough listings – especially at the lower end of the market – and fast-rising prices that are straining the budgets of prospective buyers.” (emphasis added)

The houses that are on the market are selling fast, too! According to NAR’s Realtors Confidence Index, the median number of days it took for a house to go from listed to under contract over the past three months was 34.

Bottom Line

If you are one of the many homeowners who is debating listing your house for sale this year, the time is now! Let’s get together to discuss the specifics of our market!

Millennials Flock Towards Low Down Payment Programs

Millennials Flock Towards Low Down Payment Programs | Simplifying The Market

A report released by Down Payment Resource shows that 61% of first-time homebuyers purchased their homes with a down payment of 6% or less.

The trend continued among all buyers with a mortgage, as 73% made a down payment of less than 20%.

An article by Chase points to a new wave of millennial homebuyers:

“We teamed up with Google to help us better understand what customers are searching for and how the home buying landscape is evolving. We found that millennials and first-time homebuyers are making a big splash in the market, and affordability remains top of mind.”

Among millennials who purchased homes, David Norris, Loan Depot’s Head of Retail Lending, said:

“It’s clear from the survey results that Millennials have a lot of anxiety built up about the home buying process.

There is good news, however, as there’s more flexibility than most Millennials think regarding how to qualify for a loan and what’s needed for a down payment.”

Bottom Line

If you are one of the many millennials who is debating a home purchase this year, let’s get together to help you understand your options and set you on the path to preapproval.

The Cost of Renting vs. Buying a Home [INFOGRAPHIC]

The Cost of Renting vs. Buying a Home [INFOGRAPHIC] | Simplifying The Market

The Cost of Renting vs. Buying a Home [INFOGRAPHIC] | Simplifying The Market

Some Highlights:

  • Historically, the choice between renting or buying a home has been a tough decision.
  • Looking at the percentage of income needed to rent a median-priced home today (29.2%) vs. the percentage needed to buy a median-priced home (15.8%), the choice becomes obvious.
  • Every market is different. Before you renew your lease again, find out if you can put your housing costs to work by buying this year!

Buying Remains Cheaper Than Renting in 39 States!

In the latest Rent vs. Buy Report from Trulia, they explained that homeownership remains cheaper than renting with a traditional 30-year fixed rate mortgage in the 100 largest metro areas in the United States.

The updated numbers show that the range is an average of 3.5% less expensive in San Jose (CA), all the way up to 50.1% less expensive in Baton Rouge (LA), and 33.1% nationwide!

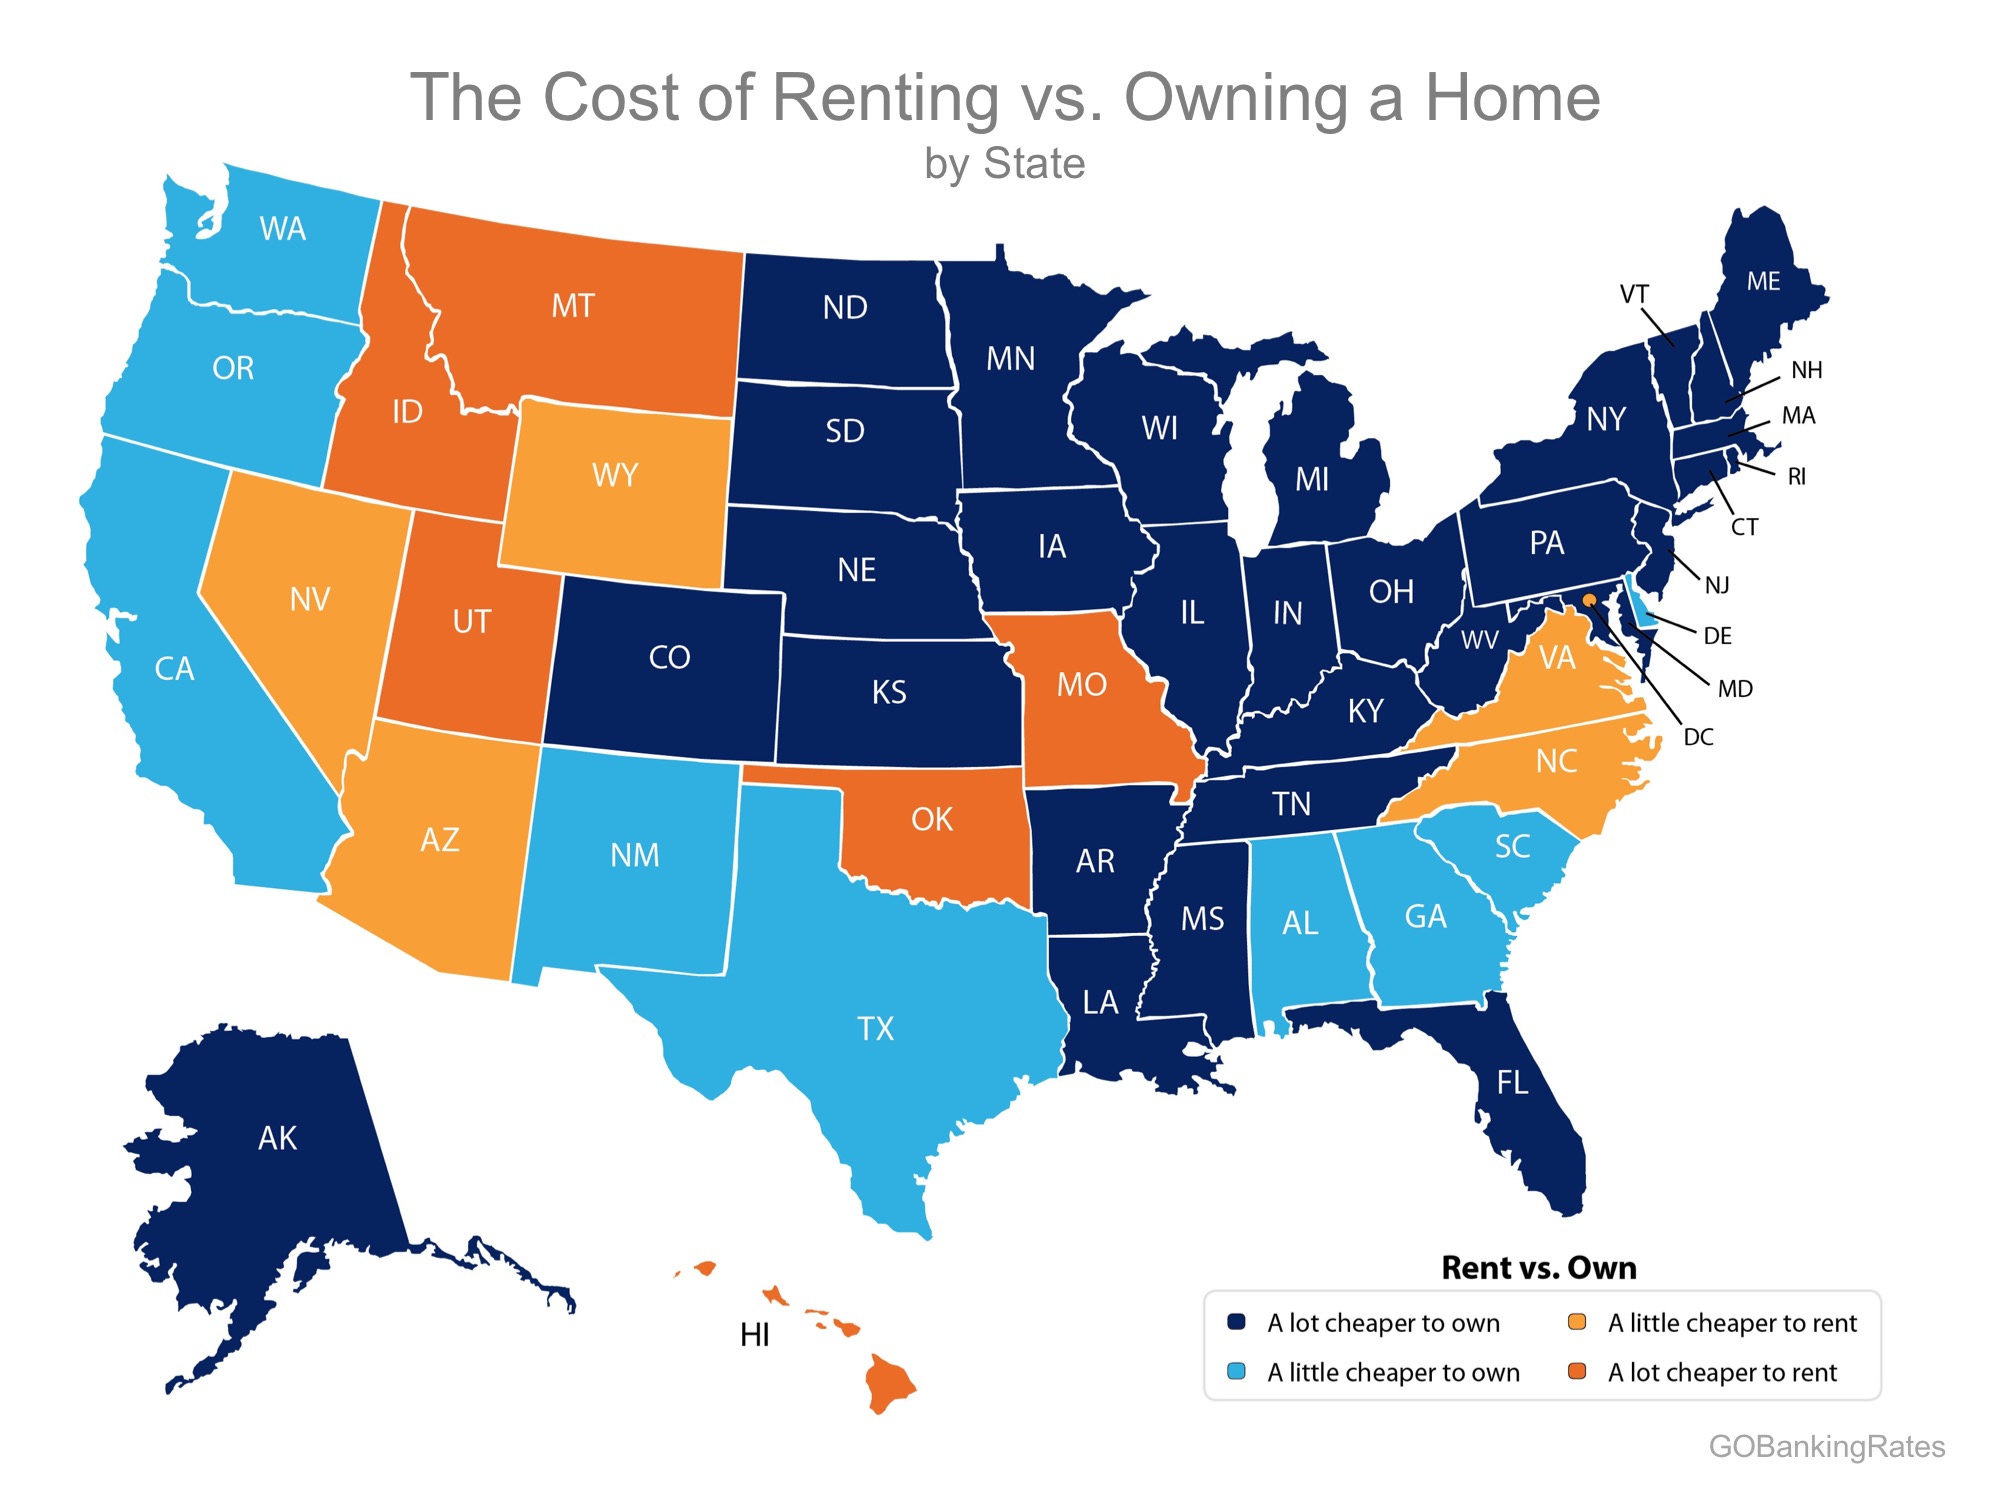
A study by GoBankingRates looked at the cost of renting vs. owning a home at the state level and concluded that in 39 states, it is actually ‘a little’ or ‘a lot’ cheaper to own (represented by the two shades of blue in the map below).

Buying Remains Cheaper Than Renting in 39 States! | Simplifying The Market

One of the main reasons owning a home has remained significantly cheaper than renting is the fact that interest rates have remained at or near historic lows. Freddie Mac reports that the current interest rate on a 30-year fixed rate mortgage is 3.91%.

Nationally, rates would have to reach 9.1%, a 128% increase over today’s average of 4.0%, for renting to be cheaper than buying. Rates haven’t been that high since January of 1995, according to Freddie Mac.

Bottom Line

Buying a home makes sense socially and financially. If you are one of the many renters who would like to evaluate your ability to buy this year, let’s get together and find you your dream home.

4 Reasons to Sell This Fall [INFOGRAPHIC]

4 Reasons to Sell This Fall [INFOGRAPHIC] | Simplifying The Market

Some Highlights:

  • Buyer demand continues to outpace the supply of homes for sale! Buyers are often competing with one another for the listings that are available!
  • Housing inventory is still under the 6-month supply that is needed for a normal housing market.
  • Perhaps the time has come for you and your family to move on and start living the life you desire.

Net Worth of Homeowners 44X Greater than Renters

Net Worth of Homeowners 44X Greater than Renters | Simplifying The Market

Every three years, the Federal Reserve conducts their Survey of Consumer Finances in which they collect data across all economic and social groups. The latest survey data, covering 2013-2016 was released two weeks ago.

The study revealed that the 2016 median net worth of homeowners was $231,400 – a 15% increase since 2013. At the same time, the median net worth of renters decreased by 5% ($5,200 today compared to $5,500 in 2013).

These numbers reveal that the net worth of a homeowner is over 44 times greater than that of a renter.

Owning a home is a great way to build family wealth

As we’ve said before, simply put, homeownership is a form of ‘forced savings.’ Every time you pay your mortgage, you are contributing to your net worth by increasing the equity in your home.

That is why, for the fourth year in a row, Gallup reported that Americans picked real estate as the best long-term investment. This year’s results showed that 34% of Americans chose real estate, followed by stocks at 26% and then gold, savings accounts/CDs, or bonds.

Greater equity in your home gives you options

If you want to find out how you can use the increased equity in your home to move to a home that better fits your current lifestyle, let’s get together to discuss the process.